The Hidden Cost of Automotive Tariffs: Why Protection Can Backfire
In March 2025, the Trump Administration imposed 25% tariffs on imported vehicles and automotive components. At first glance these policies may appear to protect American automakers; taxing foreign competitors should encourage consumers to buy American. But our research reveals a more complicated story. When you account for global supply chains—the fact that American-assembled cars often contain foreign-made parts—broad tariffs result in losses, rather than gains, for domestic producers.
This unintuitive result arises because the modern automobile industry is thoroughly globalized. Roughly half of vehicles sold in the U.S. are assembled abroad. But equally important is that many domestically assembled vehicles rely on imported parts, ranging from 25% to 90% depending on the model. When tariffs extend to imported parts, they raise production costs for domestically assembled vehicles, which both offsets the competitive advantage gained from taxing imported vehicles and reduces the number of consumers who can afford to purchase any vehicle at all.
To understand these dynamics, we developed a structural economic model of the U.S. light-duty automobile market covering 2015–2024. Our framework integrates three critical elements: how consumers choose among hundreds of vehicle models, how firms set prices under oligopolistic competition, and how tariffs on imported parts transmit through firms' cost structures.
The Data: Measuring Exposure to Foreign Inputs
Using data from the National Highway Traffic Safety Administration (NHTSA), we identified which vehicles are assembled where and how much of their parts value is imported. This granular data reveals that U.S.-headquartered firms differ dramatically in their exposure to foreign inputs. For example, some models rely on 90% imported parts, while others source primarily domestically.
We also obtained sales and pricing data from S&P Polk and vehicle characteristics from DataOne which allow us to construct a comprehensive picture of product offerings and market shares in the U.S. auto market over the past decade. It is important that our data covers recent years: over this period electric vehicles grew from negligible to 7.5% of sales, and SUVs became the dominant vehicle type, rising from 31% to 49% of purchases.
How Tariffs Propagate Through the Market
Our model captures how tariffs operate through two distinct channels:
Channel 1: The direct effect. A 25% tariff on imported vehicles directly raises their cost, making domestically assembled vehicles more competitive. Consumers substitute away from foreign cars toward American-assembled models.
Channel 2: The input-cost effect. A 25% tariff on imported parts raises costs for domestic assemblers that rely on foreign inputs. This cost increase raising prices, compressing profit margins and total sales.
The interplay between these channels determines overall incidence. To estimate how foreign input cost shocks transmit into vehicle marginal costs, we leveraged exchange-rate variation. When the dollar appreciates, imported parts become cheaper; when it depreciates, they become more expensive. By examining how vehicle prices respond to these exchange-rate shocks—conditional on each vehicle's reliance on foreign inputs—we estimated that a 1% increase in foreign parts costs leads to approximately a 0.7% increase in vehicle marginal costs, reflecting both direct cost transmission and medium-run sourcing adjustments by firms.
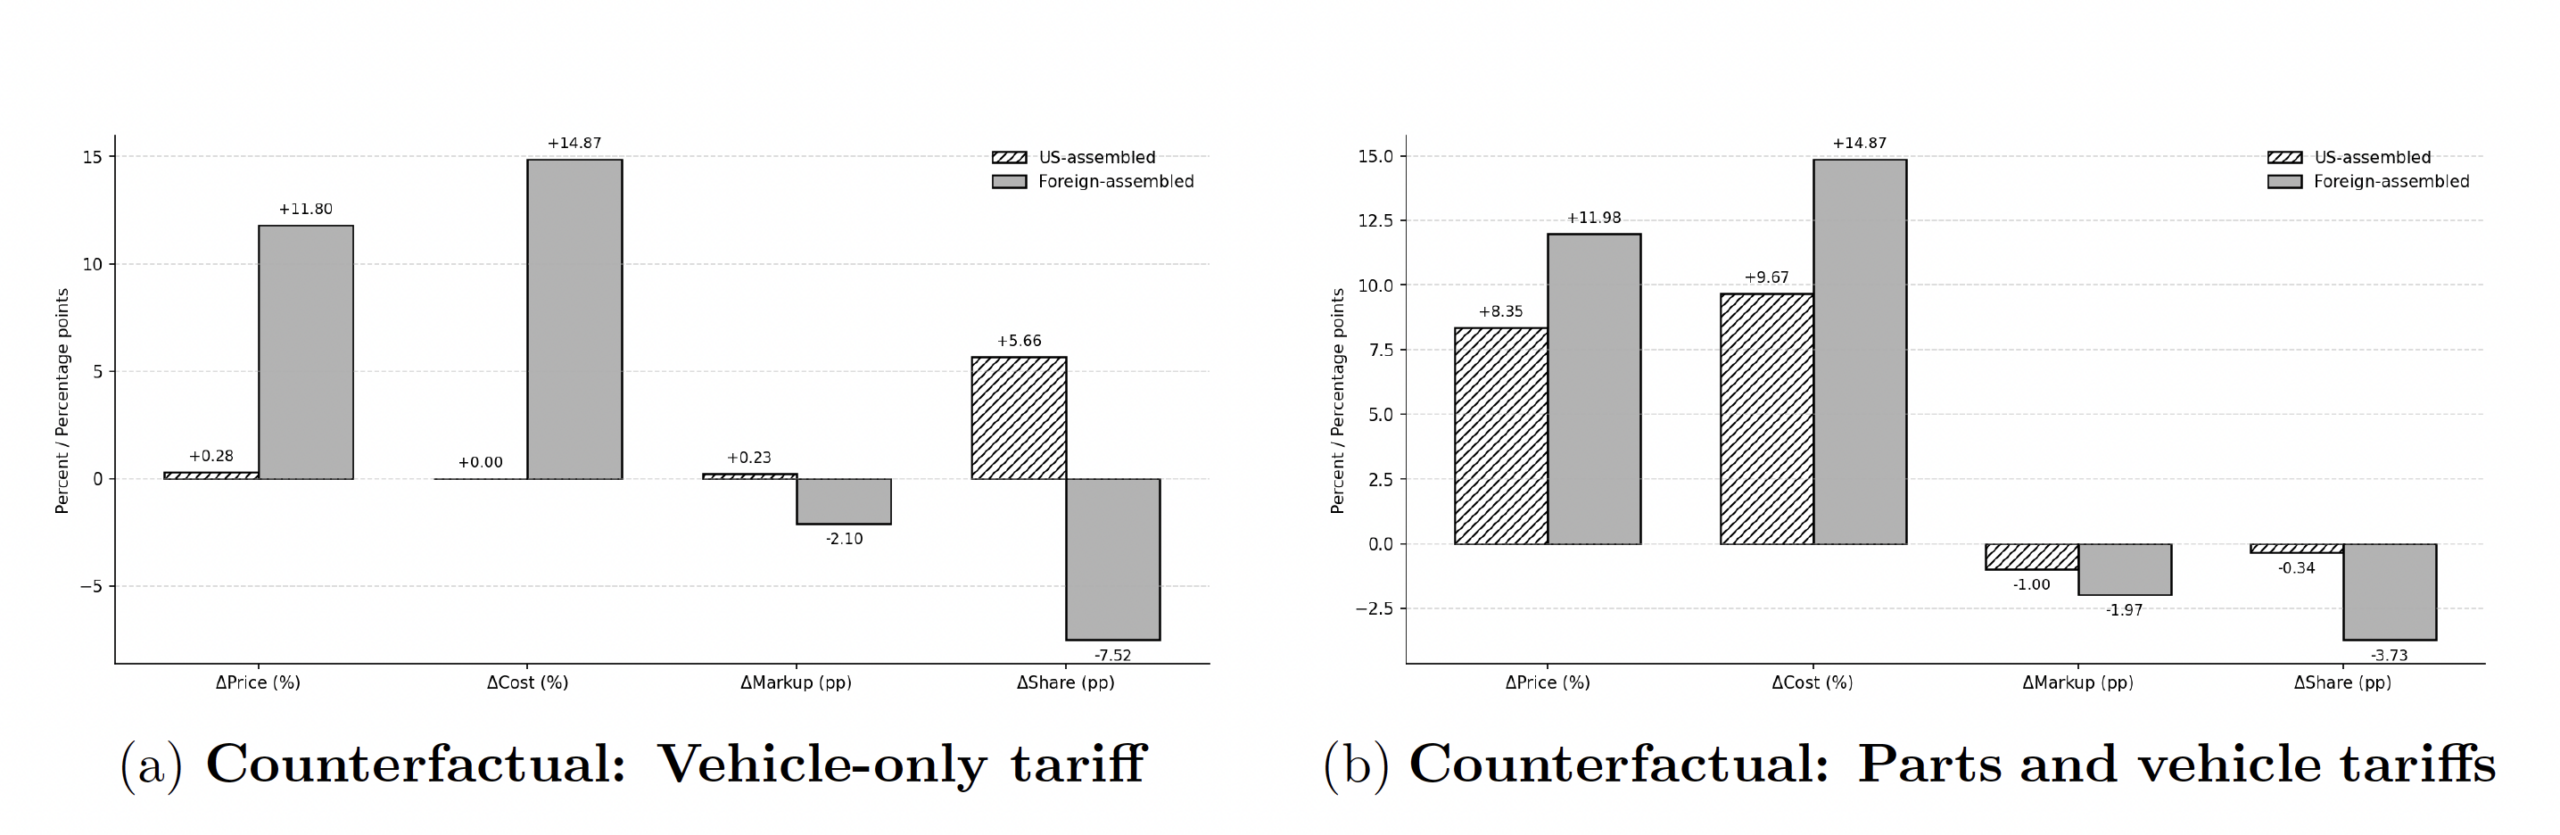
Figure 1. Changes by assembly-location: Tariff counterfactuals Tariff effects differ dramatically depending on whether tariffs apply only to finished vehicles (left panel) or to both vehicles and imported parts (right panel). Parts tariffs raise costs for U.S.-assembled vehicles, compressing markups and shifting demand to the outside option rather than reallocating from foreign to domestic assembly.
Three Key Findings
Finding 1: Vehicle-only tariffs modestly help domestic producers. A 25% tariff applied only to imported finished vehicles increases U.S. producer surplus by approximately $1 billion. U.S.-assembled vehicles gain 5.7 percentage points of market share. However, consumer surplus falls by roughly $14 billion. The policy reallocates purchasing power from consumers to producers, while tariff revenues ($15.4 billion) partially offset consumer losses.
Finding 2: Extending tariffs to parts reverses the gains. When tariffs also apply to imported automotive parts, the competitive gains for domestic producers evaporate. U.S. producer surplus declines by $2.6 billion—a complete reversal from the vehicle-only scenario. Consumer welfare losses roughly double to $32.8 billion. The reason: higher input costs make it expensive for domestic assemblers to compete, even against tariffed imports. Instead of reallocating demand toward U.S. assembly, consumers increasingly choose not to purchase vehicles at all.
Finding 3: Firm-level heterogeneity is substantial. Aggregate effects mask enormous variation across firms. Firms with lower exposure to imported parts—such as Tesla, Jeep, Honda, and Toyota—increase profits under parts tariffs. In contrast, U.S.-headquartered firms with high exposure to imported inputs (like Chevrolet, GMC, and Ford) experience profit losses. A firm's tariff incidence depends less on where its vehicles are assembled than on where its parts originate.
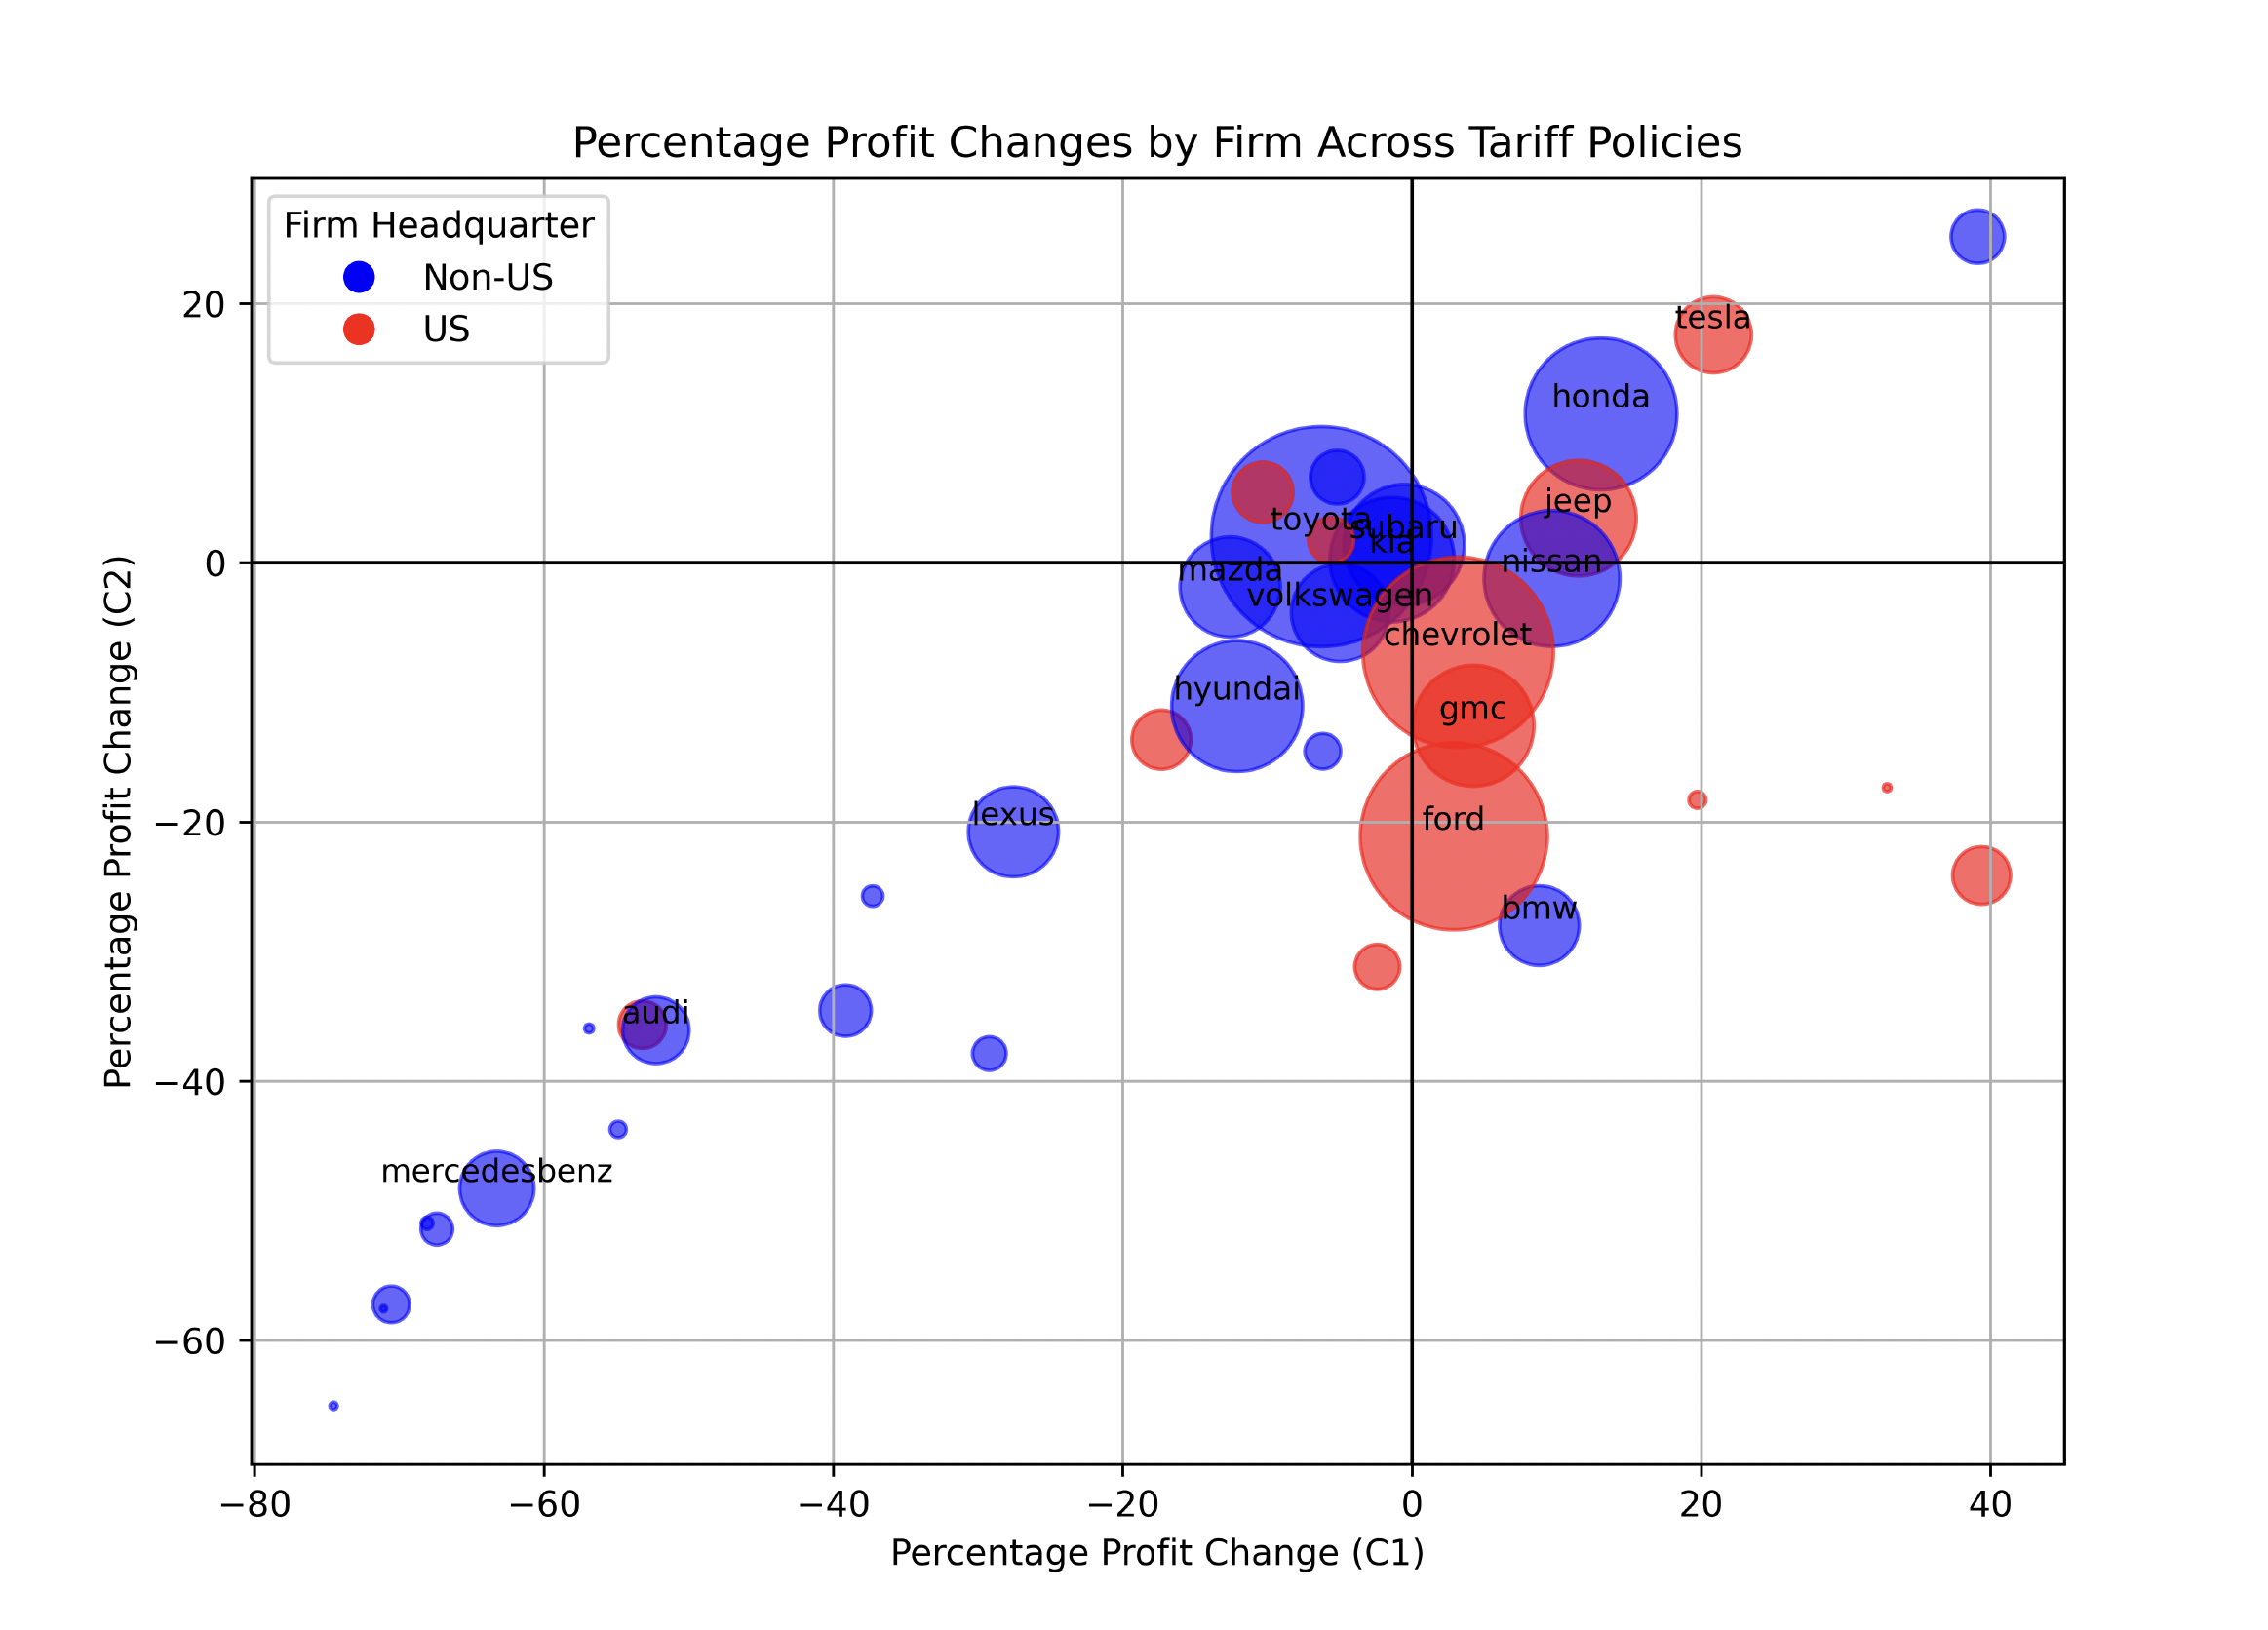
Figure 2. Percentage Profit Changes Across Firms Under Tariff Counterfactuals Firm-level profits respond heterogeneously to tariffs. The quadrant structure demonstrates the key takeaway: many U.S. firms gain under vehicle-only tariffs (bottom-right quadrant) but lose when parts tariffs are added (bottom-left quadrant). Firms like Tesla and Toyota benefit from parts tariffs due to lower foreign input exposure, while traditional U.S. manufacturers like Chevrolet and Ford lose.
Policy Implications and Trade-Offs
Our findings have several implications for policymakers:
Domestic content as much as assembly location. Policies aimed at "protecting domestic producers" cannot ignore global sourcing. A vehicle with American assembly but 80% foreign parts content is fundamentally different from one with American parts content.
Domestic outcomes are sensitive to tariff design. Selectively tariffing final goods while exempting parts could achieve locational goals (domestic assembly) with lower consumer costs. Comprehensive tariffs on both vehicles and parts harm consumers while also harming many domestic producers.
Income distribution effects are substantial. Higher-income households bear a disproportionate share of consumer welfare losses in absolute dollar terms (the top quintile loses ~$6 billion), though losses are larger in percentage terms for lower-income households.
Alternative policies deserve consideration. We also examined the Inflation Reduction Act's EV subsidies. Reinstating these subsidies increases consumer surplus by $4.8 billion and U.S. producer surplus by $1.8 billion, with net U.S. gains of near-zero once subsidy costs are factored in. Notably, EV subsidies benefit U.S. producers (especially Tesla) and increase domestic assembly—without the perverse effects of parts tariffs.
Broader Applicability
While our analysis focuses on automobiles, the mechanisms we identify are not sector-specific. Electronics, machinery, clean energy technologies, and other industries increasingly rely on global value chains and face differentiated-products competition. Policies that target both final goods and intermediate inputs—whether tariffs or subsidies—will reshape incidence through similar channels: cost exposure, firm heterogeneity, and consumer substitution.
Our work suggests that successful industrial and trade policy must engage explicitly with the reality of global supply chains. Simple protectionist intuitions—"tax imports, help domestic producers"—break down when domestic producers depend on imports. Instead, effective policy requires granular understanding of production networks, firm heterogeneity, and the mechanisms through which costs propagate through competitive markets.